Portfolio analytics and performance
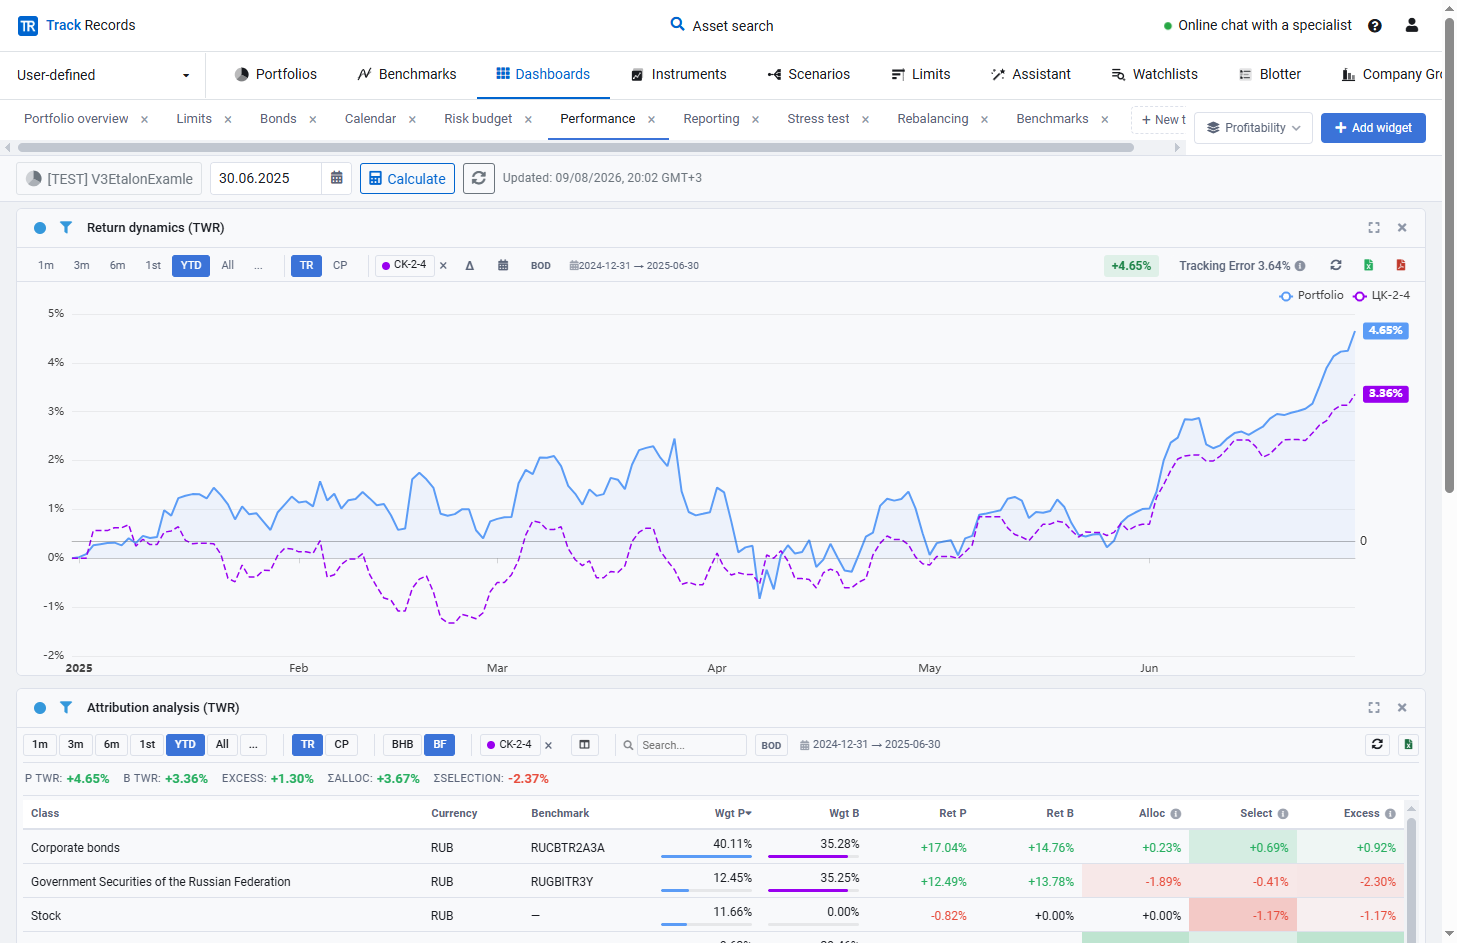
See what drives returns and what explains the gap versus the benchmark. TWR/MWR, contribution and attribution on automatically enriched portfolio data, without reconciling quotes and reference data by hand.
Who it is for
Headline return is not enough: you need the contribution of positions and the decomposition of excess return versus the benchmark. TWR/MWR, contribution and attribution run on automatically enriched portfolio data.
Snapshot portfolios load quickly for limit control and stress testing when speed matters more than a full trade history.
How accounting works
Transactions give calculation depth. Snapshots fix holdings on a date. An index or custom benchmark becomes the reference, and the portfolio is compared automatically.
Transaction-based portfolio
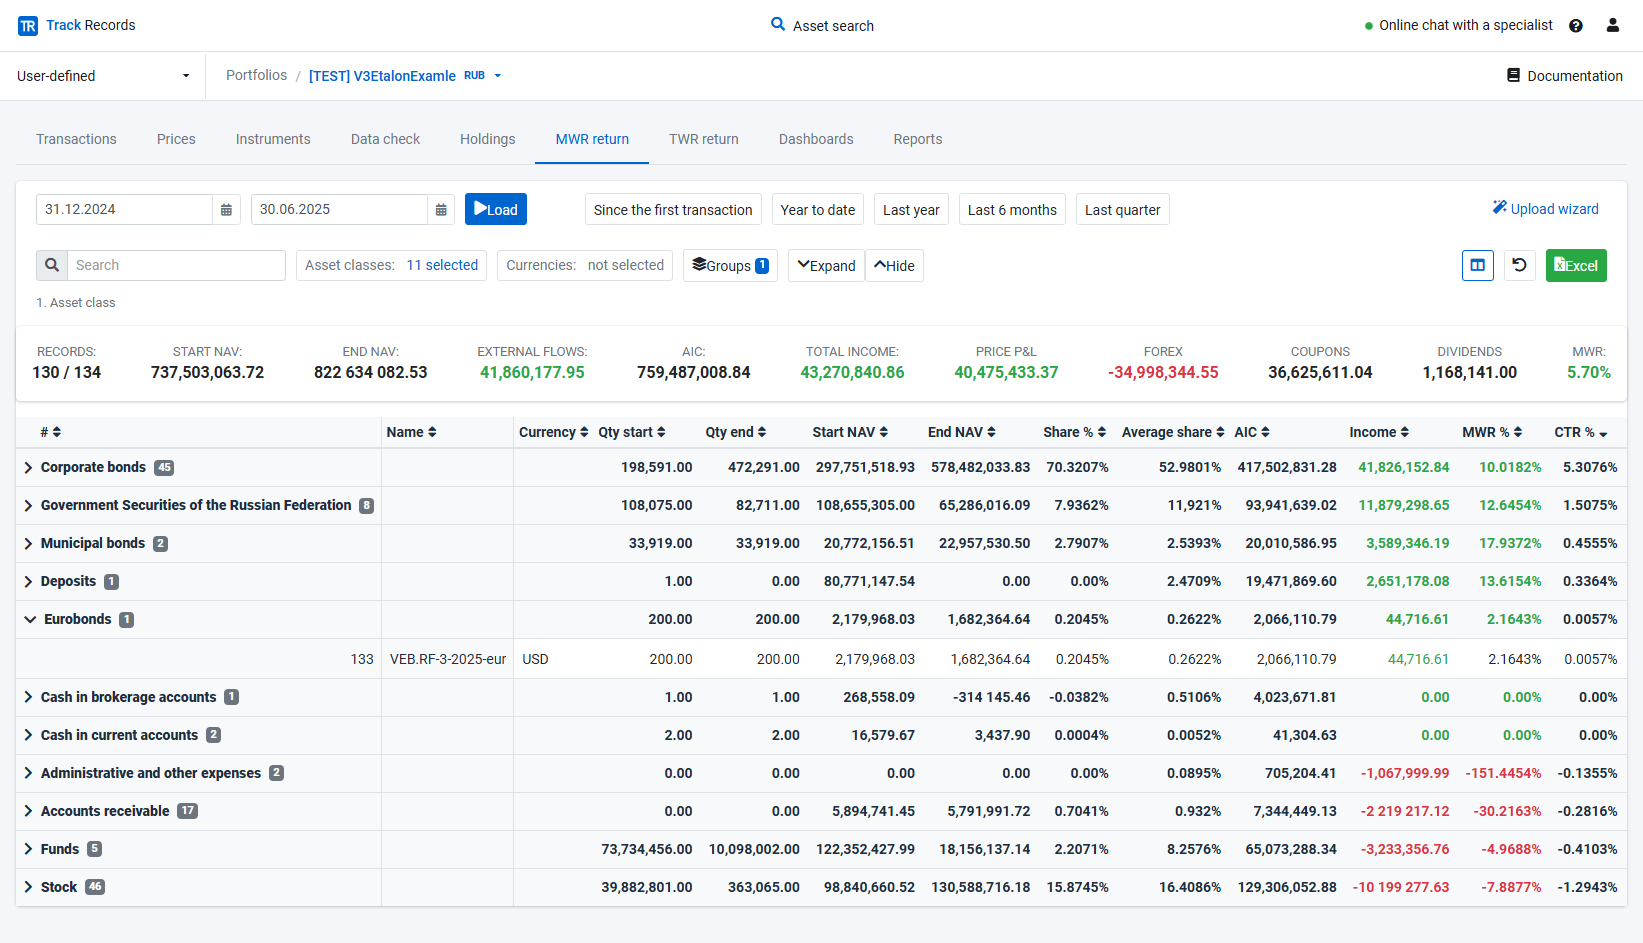
A full operations history for contribution, attribution and accurate TWR/MWR. Use it when trades, corporate actions and result decomposition matter.
- Contribution analysis by instrument
- Attribution analysis versus benchmarks
- TWR and MWR
- Breakdown by asset class, issuer, currency, sector and rating
- Income split into mark-to-market, coupons, dividends and FX
- Ready performance reports
Snapshot-based portfolio
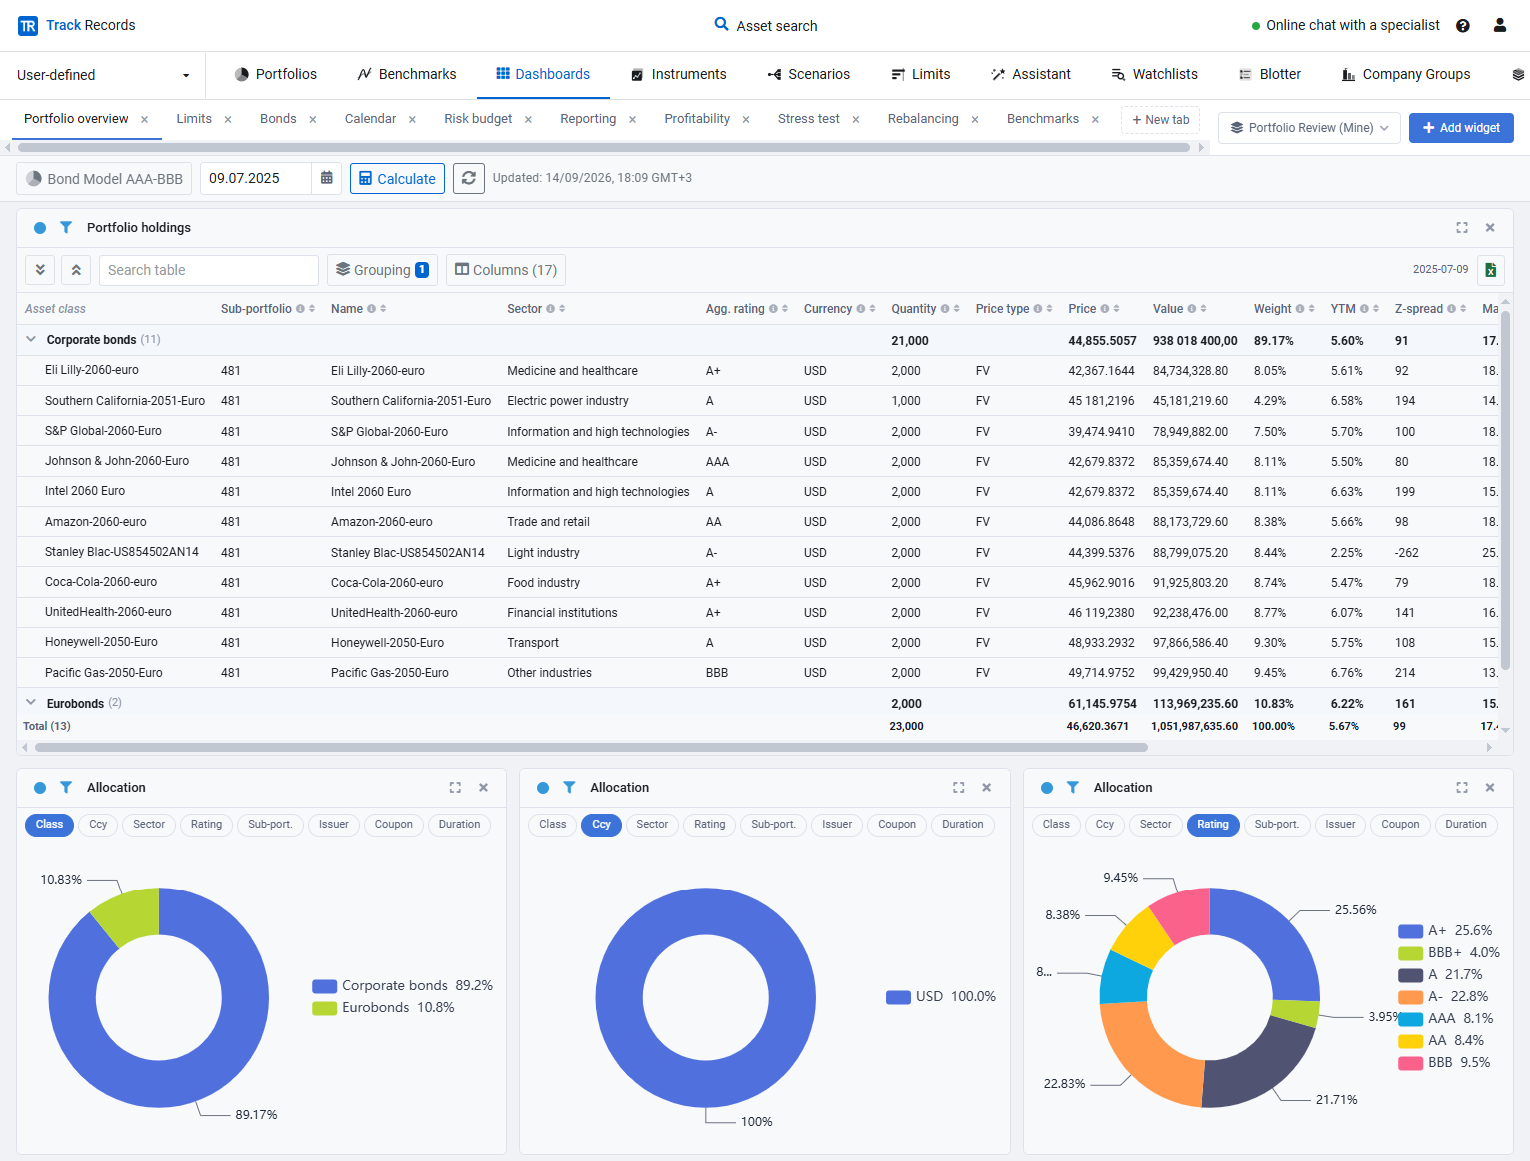
Holdings on selected dates without a full trade tape. Faster to load when you need structure, concentration and limit control rather than trade-level accounting.
- Load compositions by date without operation-level detail
- Portfolio structure and concentration
- Mandate and investment-policy limit control
- Market and credit characteristics of the book
- A practical base for scenario analysis
Team access, model portfolios and reports
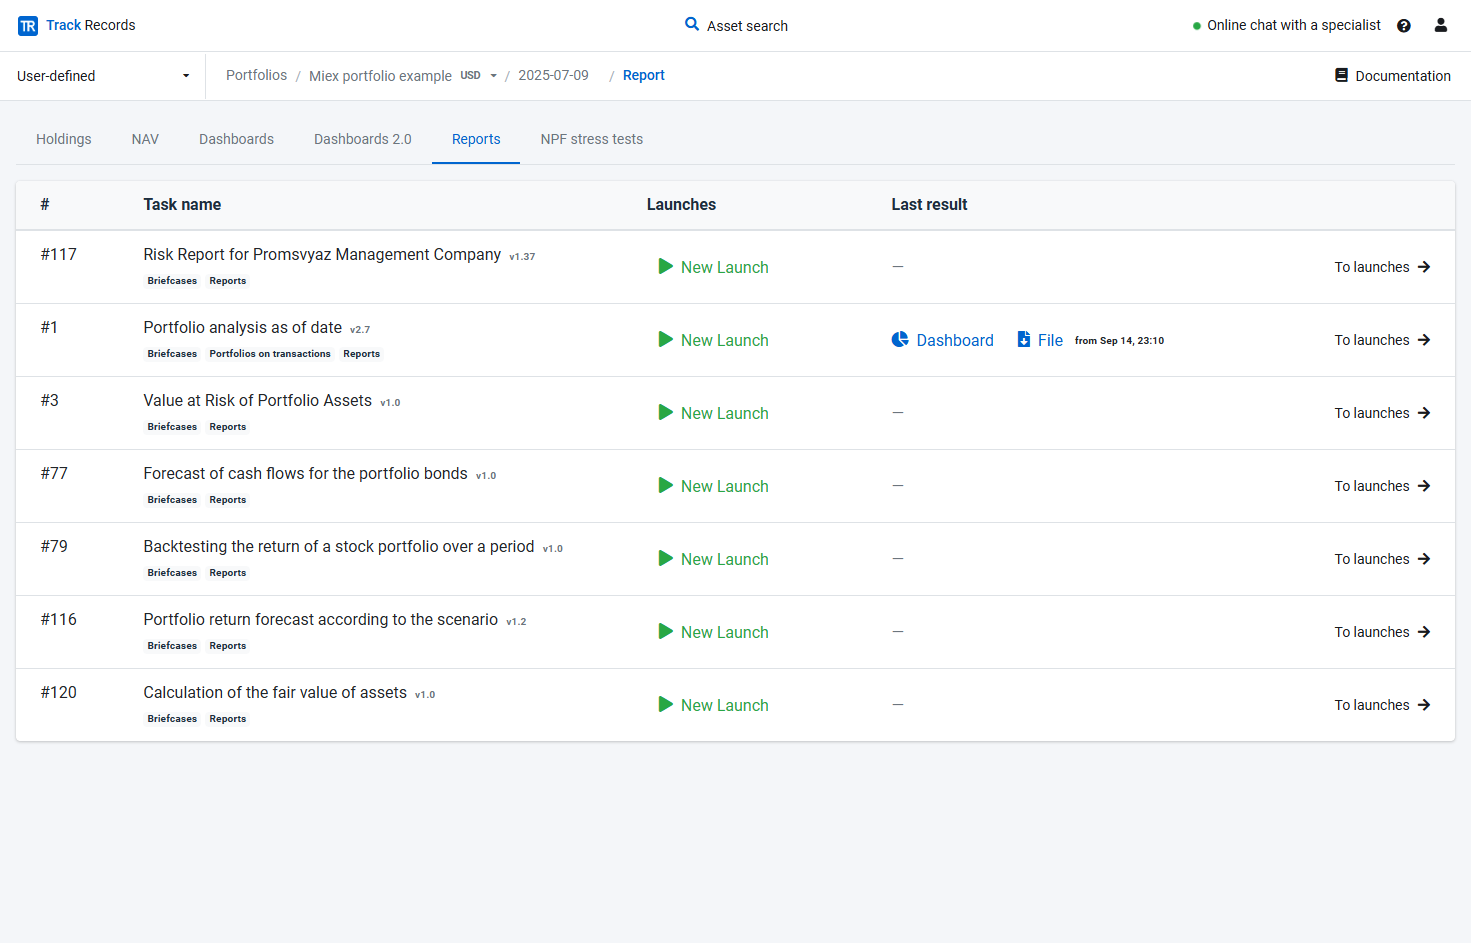
Shared access inside the team, model portfolios, cash-flow forecasts and ready reports for clients and management.
- Shared portfolio access for the team
- Model portfolios
- Scenario-based return and cash-flow forecasting
- Ready reports for clients and management
Custom benchmarks
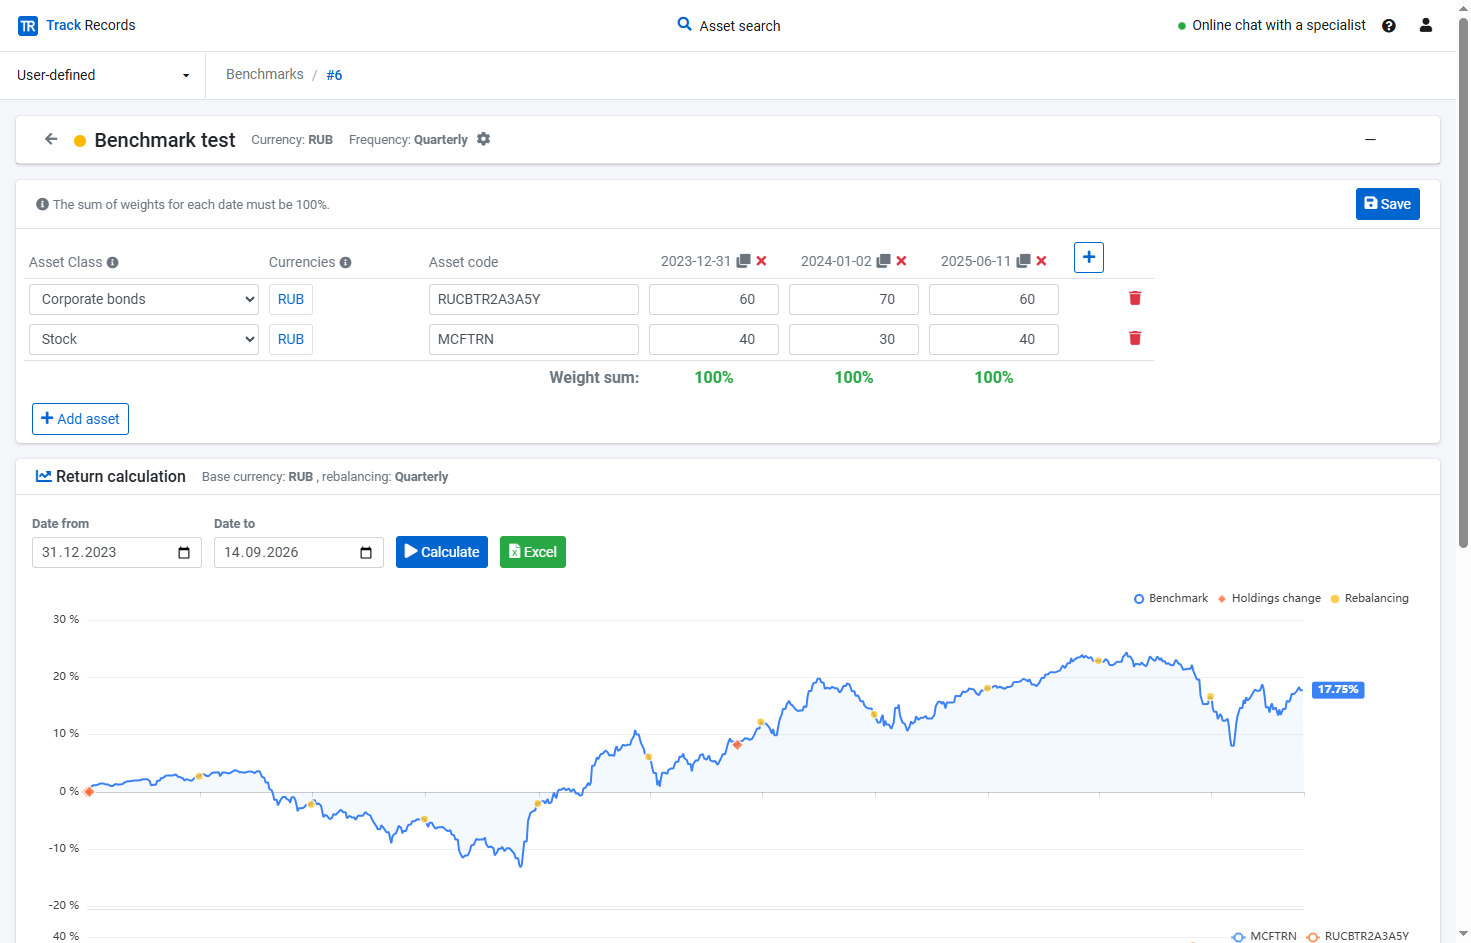
For a mixed portfolio, comparing only to an equity index distorts the result. Build a weighted benchmark from the instruments you need, set the currency, rebalancing frequency and composition changes by date. Portfolio TWR, excess-return dynamics and attribution versus that benchmark are calculated automatically.
- Index or blended custom benchmark
- Holdings with target weights
- Weights sum to 100% on every date
- Daily, monthly, quarterly rebalancing or no weight reset
- Automatic TWR comparison versus the benchmark
- Excess-return split into allocation and selection
- Rebalanced TWR and buy-and-hold
- Contribution of each asset and rebalancing timing
- Excel export of dynamics, contributions and composition legend
Pre-trade, VaR and limit sheets
Daily risk and mandate control lives on a dedicated page: market and credit risk, a limit-sheet builder, pre-trade and post-trade checks. The portfolio remains the accounting and performance layer.
Go to risk and limitsSee TrackRecords in a live demo
We'll walk you through the platform and how it fits your investment process.